On this page
Does Gold Attract Capital Gains Tax?
Yes. When you sell physical gold in Australia at a profit, the gain is subject to Capital Gains Tax (CGT) as part of your income tax return. Gold is treated as a capital asset under the Australian tax system.
This applies whether you sell gold bars, gold coins, or any other form of investment gold. The gain is the difference between what you paid (your cost base) and what you received when you sold.
CGT rules before and after 1 July 2027
For disposals before 1 July 2027, eligible Australian individuals and trusts can generally reduce a capital gain by 50% after holding the asset for at least 12 months. Companies do not receive that discount, and complying superannuation funds use a one-third discount.
From 1 July 2027, the rules change for eligible individuals and trusts. Gains accruing from that date move to CPI indexation and a 30% minimum-tax framework. For an asset already owned at the start date, the pre- and post-start-date gain components receive transitional treatment; a later sale does not automatically put the whole lifetime gain under the new method.
Holding period, capital losses, ownership structure and the accepted start-date value can change the result. Read the 2026 CGT changes article and obtain advice for your circumstances.
Investment Coins vs Collectible Coins
The ATO makes an important distinction between investment gold coins and collectible coins.
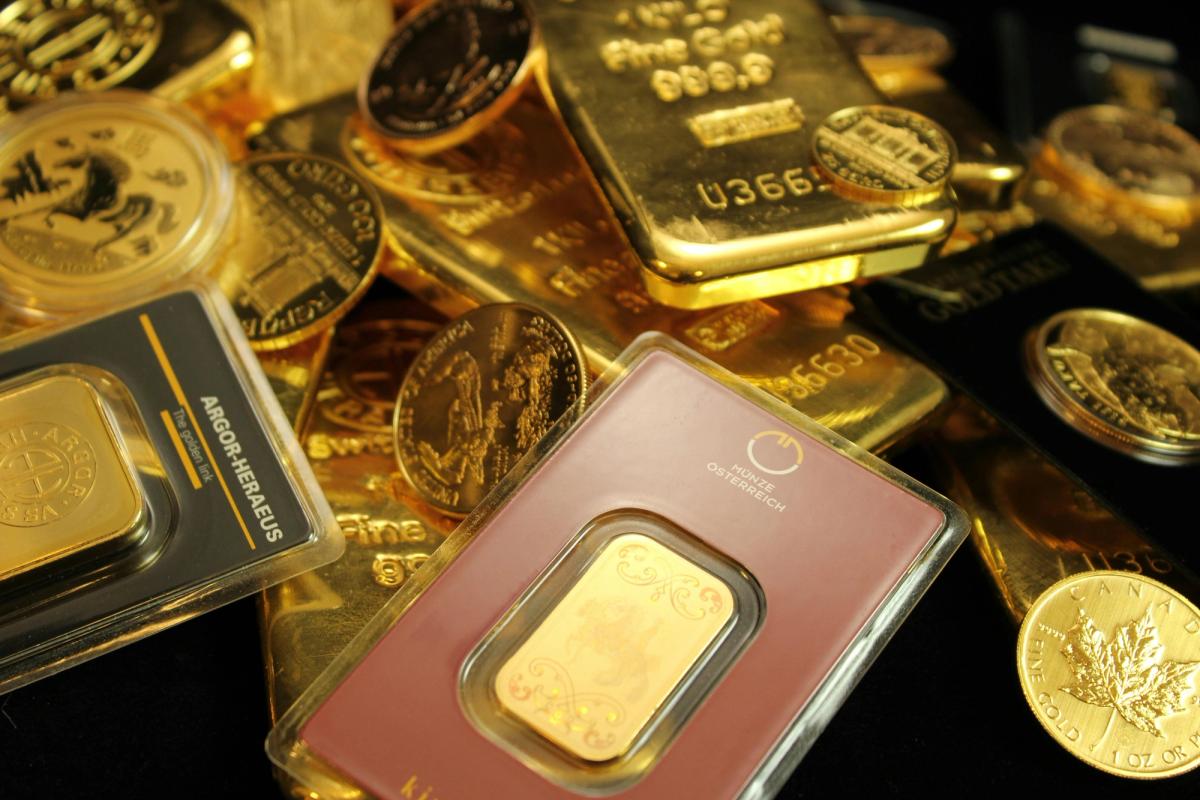
Investment gold coins such as Perth Mint Kangaroos, Maple Leafs, and Philharmonics are treated as standard capital assets. CGT applies normally, and the 50% discount is available for holdings over 12 months. These products are all listed on our gold coins comparison page.
Collectible coins including proof sets, commemorative issues, and coins with significant numismatic premium are treated differently. Under ATO rules, collectibles acquired for $500 or less are disregarded for CGT. Losses on collectibles can only offset gains from other collectibles, not general capital gains.
For standard bullion coins bought at close to spot price, the ATO will generally treat them as investment assets. If you are buying rare proof coins or coins trading well above melt value, seek tax advice.
Cost Base: What You Can Include
Your cost base for CGT purposes includes:
- The purchase price of the gold
- Dealer fees, brokerage, or shipping and insurance costs at the time of purchase
- Storage costs (where they are incurred to maintain the investment)
- The cost of authenticating or valuing the gold
Keep all receipts, invoices, and transaction records from the moment you buy. This is critical if you are ever audited. The ATO requires records to be kept for at least five years after the asset is sold.
Capital Losses on Gold
If you sell gold at a loss, you have a capital loss. Capital losses can only be offset against capital gains, not against other income like salary or business income.
Unused capital losses can be carried forward indefinitely to offset future capital gains. This can be useful if you sell gold in a down year and then realise other capital gains in future years.
Gold in a Company or Trust
If you hold gold through a company, the 50% CGT discount is not available. Companies pay a flat 30% (or 25% for small businesses) on all capital gains, regardless of holding period.
Trusts can access the 50% discount if the gain is distributed to individual beneficiaries who have met the 12-month holding requirement. SMSF rules are different. See our SMSF gold guide for full details on the significant tax advantages of holding gold inside super.
Record Keeping Requirements
The ATO requires you to keep records of all capital asset transactions for at least five years after the asset is sold. For gold, this means:
- Purchase invoices or receipts from the dealer
- Proof of payment (bank statement, transfer confirmation)
- Sale receipts or buyback confirmation from the dealer
- Any storage or insurance receipts included in the cost base
If you buy and sell frequently, use a spreadsheet or accounting software to track your cost base, holding period, and gains/losses. CGT becomes complex quickly with multiple lots purchased at different times and prices.
To start comparing prices before your next purchase, see our live gold price comparison tables.
General information, not financial or tax advice. Figures in the text reflect the time of writing; prices elsewhere on this site are live.
Editorial standards →